

VAT on Corporate Gifts in the UAE: The AED 500 Rule and 5 Worked Examples (2026)

Yes. Corporate gifts bought in the UAE carry 5% VAT, which a VAT registered business can usually recover on client gifts. Giving a gift away free can count as a deemed supply, but not when goods given to one recipient stay within AED 500 in 12 months, or total output tax on deemed supplies stays within AED 2,000.
That is the short answer, and this VAT on corporate gifts UAE guide shows exactly where each number comes from. On 19 November 2026 we read the current texts published by the Federal Tax Authority: Federal Decree-Law No. 8 of 2017 on VAT and its Executive Regulation (Cabinet Decision No. 52 of 2017, as amended up to Cabinet Decision No. 149 of 2026). Below you will find the rules in plain English, worked examples for gifts of AED 50, AED 200 and AED 600, the line between gifts and entertainment, and the records to keep.
If you are planning a gifting round now, our bulk order team can quote gifts per recipient so the numbers are easy to track.
This guide explains the published rules for finance and HR teams. It is not tax advice; confirm how they apply to your company with your tax adviser or the Federal Tax Authority.
VAT on corporate gifts UAE: the rules in one table
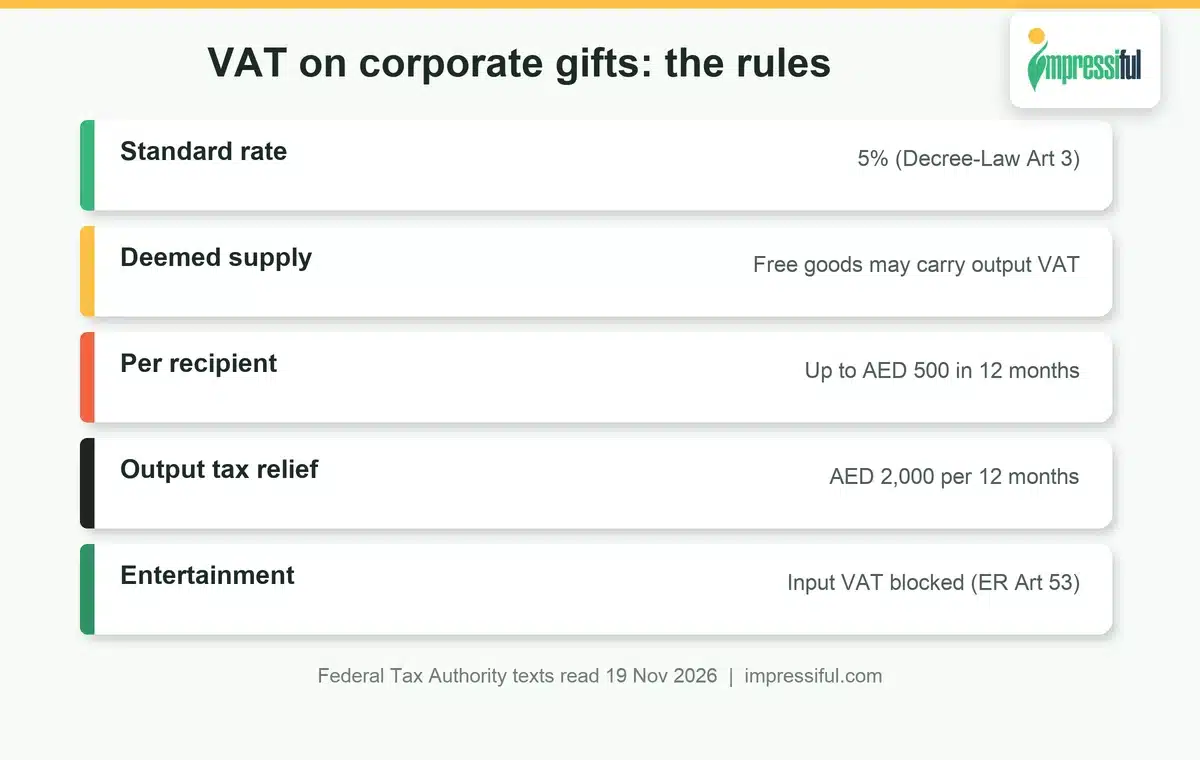
Five provisions decide the VAT on corporate gifts in the UAE. The standard rate is set by the Decree-Law, the deemed supply rules sit in Articles 11 and 12, and the money limits are in Article 5 of the Executive Regulation.
| Rule | Where it is | What it means for corporate gifts |
|---|---|---|
| 5% standard rate | Decree-Law, Article 3 | Gifts you buy from a UAE supplier carry 5% VAT on the invoice. |
| Deemed supply | Decree-Law, Article 11 | Goods on which you recovered input VAT, then gave away or used outside the business, can be treated as a supply you made, so output VAT may be due. |
| AED 500 per recipient | Decree-Law Article 12(4) and Executive Regulation Article 5(1) | No deemed supply where goods are given as samples or commercial gifts and the value to each recipient does not exceed AED 500 within 12 months. |
| AED 2,000 output tax | Decree-Law Article 12(5) and Executive Regulation Article 5(2) | Total output tax on all your deemed supplies is relieved up to AED 2,000 per supplier per 12 months; amounts above it are payable tax (AED 250,000 for government entities and charities supplying each other). |
| Blocked input tax | Executive Regulation, Article 53 | VAT on entertainment for non-employees, and on goods for employees’ personal benefit, is generally not recoverable, with listed exceptions. |
Two more details matter. If you did not recover the input VAT in the first place, there is no deemed supply at all (Decree-Law Article 12(1)). And where a deemed supply does arise, its value is the total cost you incurred, not the retail price (Decree-Law Article 37).
Planning a branded order?
Share your quantities, budget and deadline. We reply with options, mockups and a bulk price, plus free design help.
How the AED 500 rule works
The AED 500 line is the one most finance teams meet first. It applies per recipient, not per gift, and it covers the total value of goods given to that recipient within 12 months. Three points are easy to miss:
- It is cumulative. A client who receives an AED 200 gift at Eid, another at National Day and a third at year end has received AED 600 in goods, which is over the line.
- The 12 months are fixed by the regulation. Article 5(3) of the Executive Regulation defines the period as the 12 months preceding the end of the month in which you make the supply. Several online summaries describe it loosely as a “rolling” year; the official wording ties it to month ends, so set your gift register up by month.
- It covers goods given as samples or commercial gifts. Branded merchandise, gift sets, drinkware and desk items for clients fit this description. Services, such as event tickets or dinners, are treated differently (see the entertainment section below).
For most client gifting, staying within AED 500 per person per year is simple: one or two well chosen gifts per client, and a register that adds them up. Our corporate gift budget guide shows how to set an amount per person and per occasion.
Worked examples: AED 50, AED 200 and AED 600 gifts
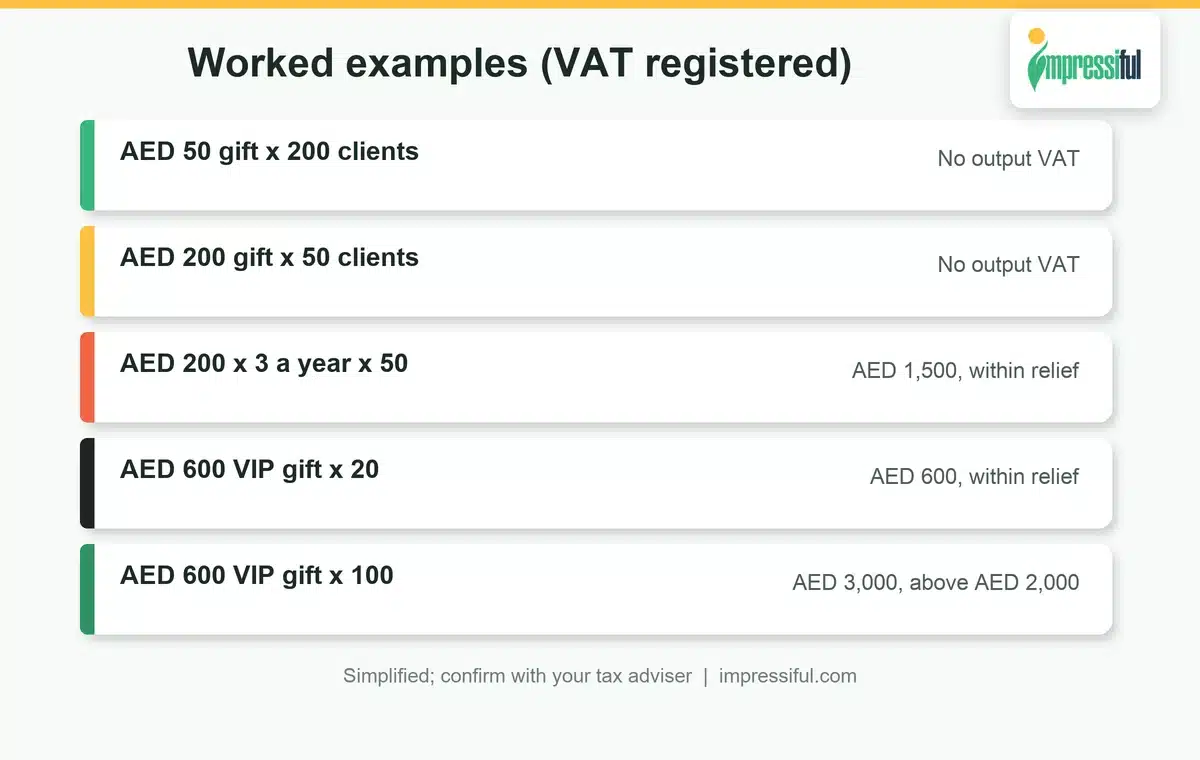
The examples below assume a VAT registered company that buys gifts from a UAE supplier, holds a valid tax invoice and recovers the input VAT. Values are before VAT. They are simplified to show how the rules interact; your adviser will apply them to your own records.
| Scenario | Input VAT paid (5%) | Over AED 500 per recipient? | Output VAT on deemed supply |
|---|---|---|---|
| AED 50 gift to 200 clients (AED 10,000) | AED 500 | No (AED 50 each) | None: covered by the AED 500 rule |
| AED 200 gift to 50 clients, once a year (AED 10,000) | AED 500 | No (AED 200 each) | None: covered by the AED 500 rule |
| AED 200 gift to the same 50 clients three times a year (AED 30,000) | AED 1,500 | Yes (AED 600 each) | AED 1,500 calculated (5% of cost), which is within the AED 2,000 relief if it is your only deemed supply |
| AED 600 VIP gift to 20 clients (AED 12,000) | AED 600 | Yes | AED 600 calculated, within the AED 2,000 relief if nothing else is deemed |
| AED 600 VIP gift to 100 clients (AED 60,000) | AED 3,000 | Yes | AED 3,000 calculated; the regulation treats the amount above AED 2,000 as payable tax |
Two lessons follow. First, gifts of AED 500 or less per client per year usually create no output VAT at all. Second, the AED 2,000 relief is a single allowance for all your deemed supplies, including items such as business assets used privately, so it can be used up by things that have nothing to do with gifts. Check the total with your accountant before a large VIP round.
Can you recover VAT on gifts? Clients, employees and entertainment
Whether you can claim back the 5% depends on who receives the gift and what it is.
Gifts to clients and prospects
Branded goods given to clients and prospects are bought for the business, so the input VAT is generally recoverable with a valid tax invoice, subject to the deemed supply rules above. Ask every supplier for a tax invoice showing their tax registration number and the VAT amount, and file it with your gift register. If you are weighing a factory order abroad, our guide on whether to import promotional products from China shows how customs duty and import VAT add up.
Entertainment is not a gift
Article 53 of the Executive Regulation blocks input VAT on entertainment provided to anyone you do not employ, including customers and potential customers. It defines entertainment as hospitality of any kind: accommodation, food and drink outside a normal meeting, access to shows or events, and trips for pleasure. A client dinner or concert tickets therefore follow the entertainment rule, while a branded flask or notebook follows the gift rules.
Gifts to employees
Article 53 also blocks input VAT on goods bought for employees for no charge and for their personal benefit, unless an exception applies: the goods are required by UAE labour law, they are needed for the job under a contract or documented policy and are normal business practice, or the provision is itself a deemed supply. A birthday or farewell gift is personal; a uniform or a laptop bag needed for work is not.
From 1 October 2026, FTA Decision No. 17 of 2026 sets conditions for recovering VAT on six employee expense types (transport, food in remote locations, accommodation, temporary housing for new joiners, phones and data, and parking). Gifts are not on that list, so treat staff gifts under the Article 53 rules.
Planning staff gifts this season? Our corporate gifts for employees guide covers ideas and budgets.
Records to keep for VAT on corporate gifts
Good records are what make the AED 500 and AED 2,000 lines usable. Keep these together for each gifting round:
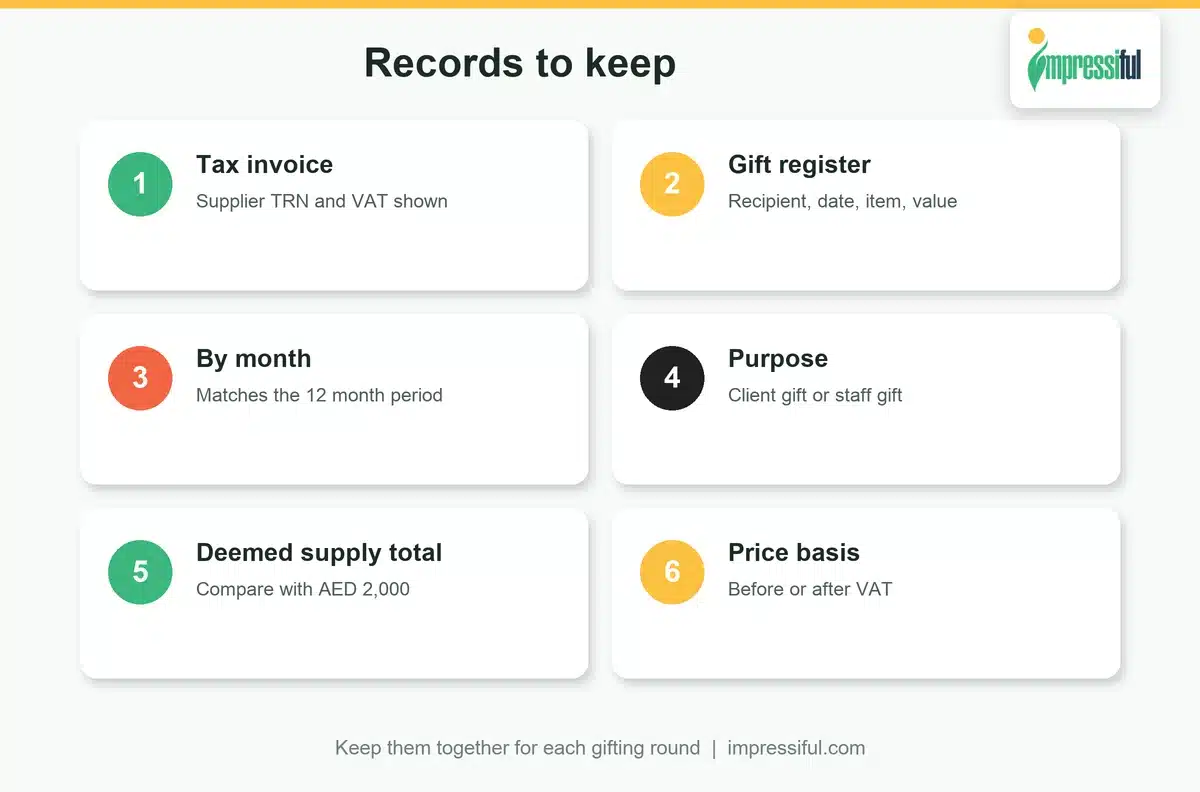
- The supplier’s tax invoice, with their tax registration number, the VAT charged and a description of the goods.
- A gift register listing each recipient, their company, the date, the item and the value before VAT, summarised by month to match the 12 month period in Article 5(3).
- The purpose of each round (client thank you, event giveaway, staff recognition), so client gifts and employee gifts are not mixed.
- A running total of output tax on deemed supplies for the business, to compare with the AED 2,000 relief.
- Price basis: the Decree-Law (Article 38) requires advertised prices to include VAT, but business quotes are often shown before VAT. Note which basis each quote uses so totals are comparable.
How to plan a gifting round that keeps VAT simple
- Set a per recipient cap of AED 500 or less per year for client gifts, and split it across your occasions.
- Use one supplier per round so all gifts sit on one tax invoice with a clear item list.
- Brand the gift, not the experience: a branded flask, notebook or gift set is a commercial gift, while tickets and meals are entertainment.
- Keep VIP gifts separate and check the AED 2,000 total before you order.
- Order in bulk: up to 60% off from 100 pieces, 25% off a first order with WELCOME25, and free shipping from AED 500 lower the cost per recipient. Current offers are on our promotions page.
Not sure what to give? Our corporate gift etiquette guide explains what is appropriate in the UAE, and our range of corporate gift sets shows live prices per item.
Frequently asked questions
Is there VAT on corporate gifts?
Yes. Corporate gifts bought from a UAE supplier carry VAT at the standard rate of 5%, set by Article 3 of Federal Decree-Law No. 8 of 2017. Giving the gifts away can also trigger output VAT as a deemed supply, unless the value to each recipient stays within AED 500 in 12 months or your total deemed supply output tax stays within AED 2,000. Read the texts on the FTA legislation page.
Can I claim VAT back on gifts to clients?
Usually, yes. A VAT registered business can generally recover the input VAT on branded goods given to clients when it holds a valid tax invoice, because the gifts are bought for the business. The exception is entertainment, such as meals, event access or trips, where Article 53 of the Executive Regulation blocks recovery. Keep a gift register so you can show the AED 500 per recipient limit was respected.
Can we claim VAT on gifts?
It depends on the recipient. For client gifts, input VAT is generally recoverable, with the deemed supply rules applying above AED 500 per recipient. For gifts to employees for their personal benefit, such as birthdays or farewells, Article 53 generally blocks recovery unless an exception applies. Our gift budget guide helps you plan amounts per person.
What are the exempt items from VAT in the UAE?
Article 46 of the VAT Decree-Law exempts four kinds of supply: certain financial services, residential buildings sold or leased (other than zero rated first supplies), bare land, and local passenger transport. Corporate gifts and merchandise are not exempt; they are standard rated at 5%. Exempt is also different from zero rated, which covers items such as exports, so check the category with your adviser.
Get a quote that is easy to account for
Tell us the gift, the number of recipients, your budget per person and your date, and we will send a written quote per item and in total, so your gift register and VAT checks are simple.
Get a free quote for corporate gifts
Prefer WhatsApp? Message +971 52 656 8355. Our office is at Office C1-1F-SF3340, Ajman Free Zone C1 Building, Ajman, UAE, open Monday to Saturday, 9:30am to 7pm.